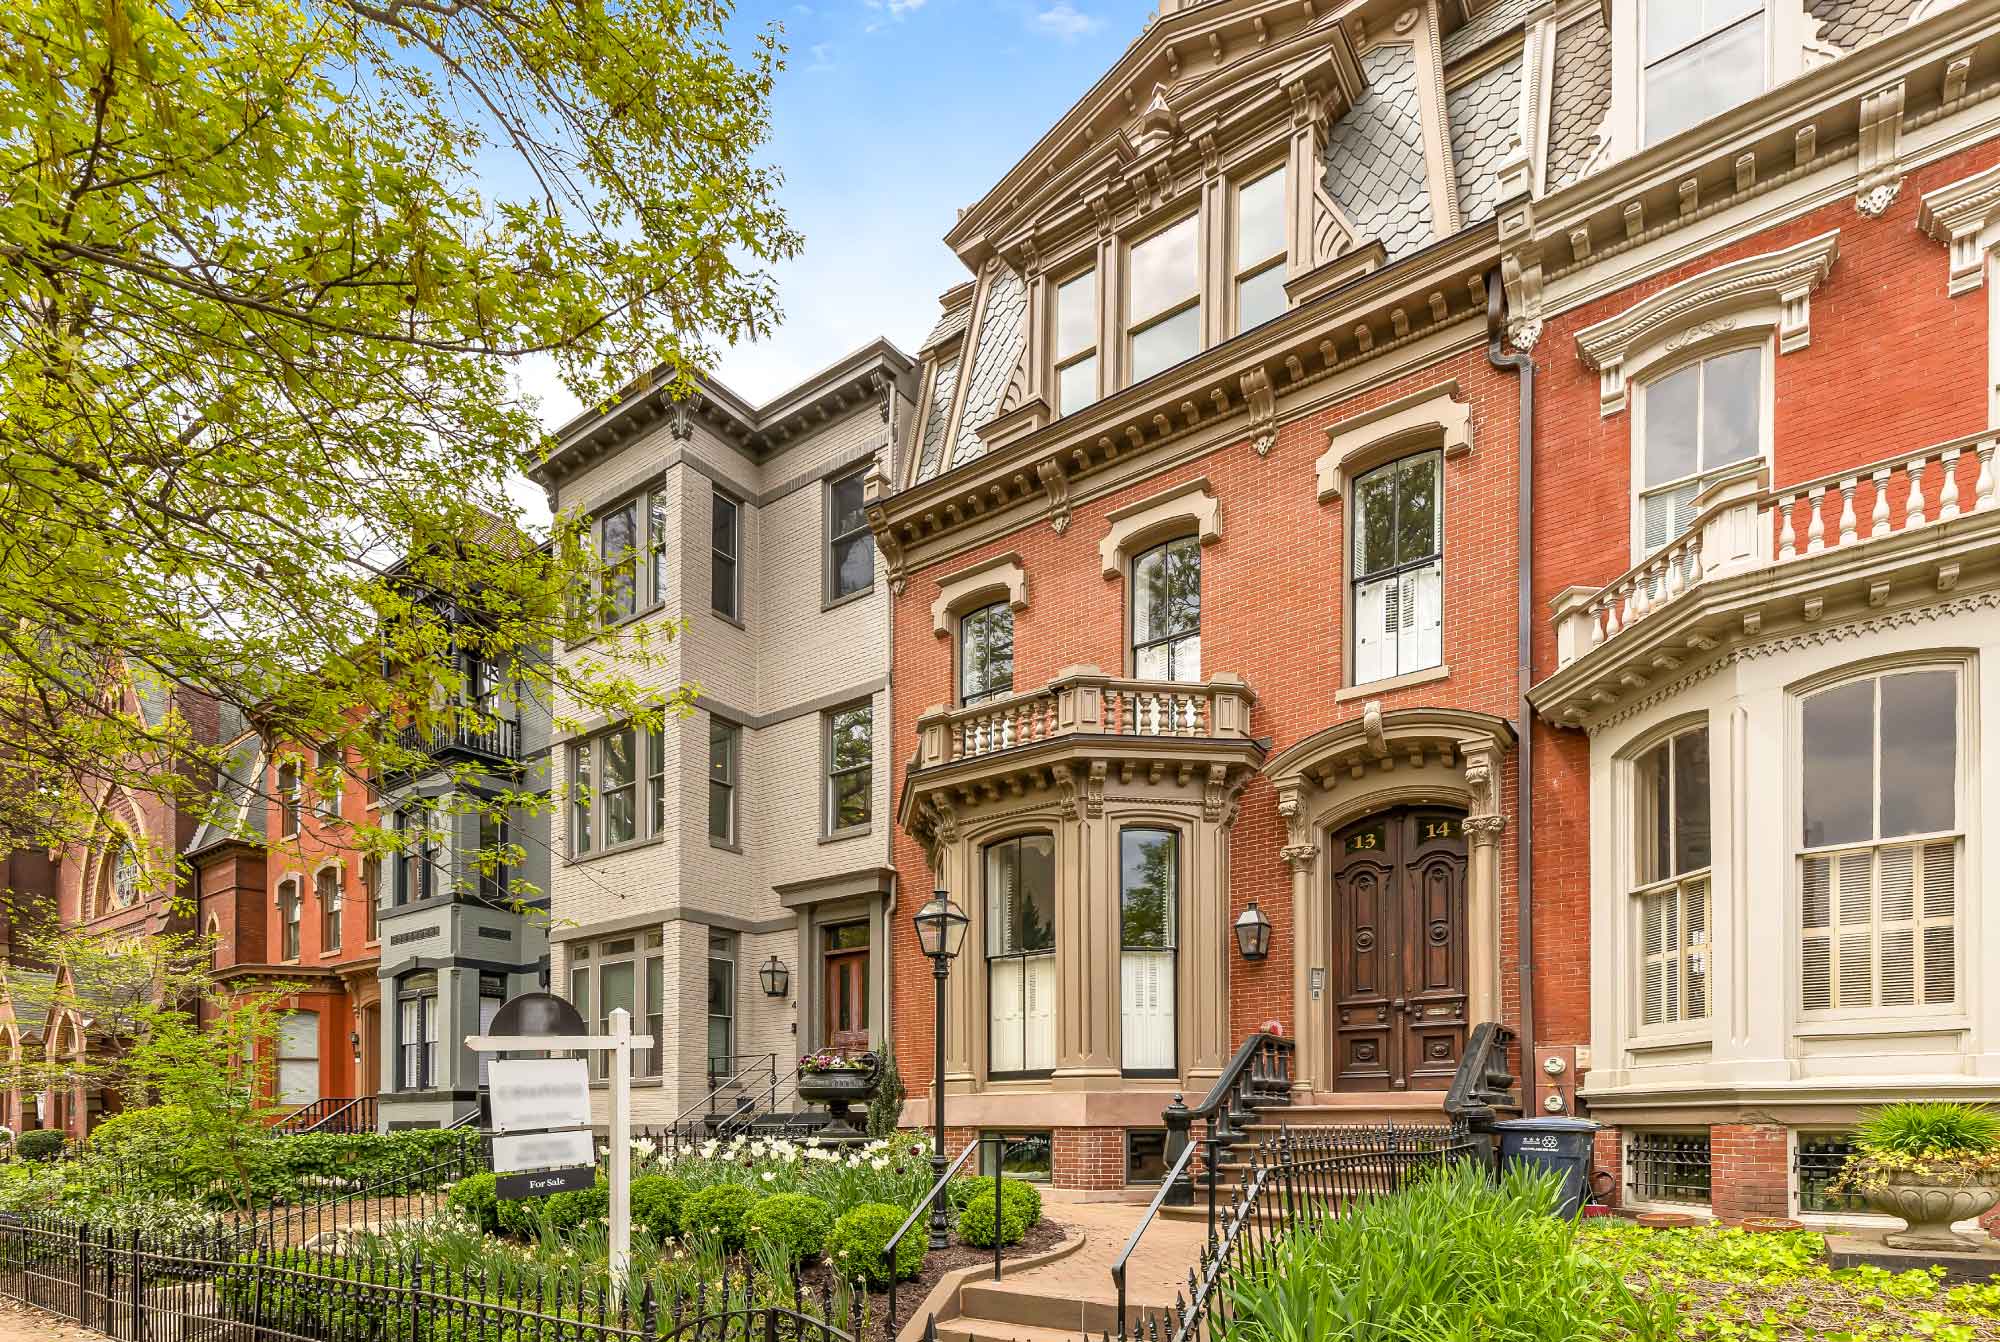
Opinion: Why I Would Buy DC Region Real Estate Now
By Jenn Smira | Founder and CEO, Jenn Smira & Co. at Compass
If you’ve been waiting for a sign that it’s time to buy a home in Washington, DC, Maryland, or Northern Virginia, here’s my take: The opportunity isn’t on the horizon; it’s already arrived. For buyers who can comfortably afford today’s mortgage payments, I believe the time to act is now.
After more than 18 years in real estate, I’ve learned that confidence (or lack thereof) can be just as influential as market conditions. Buyers may find a home they love, but still hesitate when uncertainty prevails around their job, their organization’s funding, or where the economy is headed. But when that uncertainty begins to lift, the decision to move becomes easier. And with more buyers ready to make a move in the coming months, the negotiating power available today may become increasingly harder to unlock.
Why I’m Optimistic About What’s Ahead
The blue wave across the country has only strengthened my conviction about the future of our region’s housing market. My prediction? Jobs will return, young professionals will come back, and nonprofit funding will rebound. Washington has always been a magnet for ambitious people drawn to careers in public service, research, and advocacy. As confidence in those opportunities returns, I believe we’ll see renewed energy throughout the region, with housing demand following close behind.
Of course, a recovery of this scale won’t happen overnight. A change in Congress doesn’t automatically restore lost positions, replenish grants, or reverse economic uncertainty; meaningful progress requires tangible hiring, funding decisions, and time. But that’s precisely why I believe today’s market brings promise.
And by the time a recovery becomes obvious to everyone, some of the advantages available to buyers now may already be gone.
Looking to buy a home in DC? Add these topics to your lineup!
A Closer Look at Today’s Housing Market
While the DC area’s housing markets are far from identical, recent figures reveal several encouraging signs for prospective buyers.
Consider September’s numbers:
- Washington, DC: The median sold price was $660,000, a 2.9% decrease from the previous year, with homes spending an average of 46 days on the market.
- Montgomery County, MD: The median sold price reached $610,000, up 1.8% year over year, while homes averaged 34 days on the market.
- Prince George’s County, MD: The median sold price remained steady at $450,000, even as closed sales declined 12.7%.
- Northern Virginia: Active inventory across the NVAR region increased by more than 30%, with condo and townhome inventory climbing nearly 50%.
What does this mean for buyers? In certain segments of the market, greater selection is creating something that hasn’t always been easy to come by: breathing room. More available homes can translate into more time to evaluate properties, compare options, assess condition, and negotiate with sellers. That doesn’t mean prices are declining across the board, nor would I suggest that the entire region has returned to 2018 values. Every neighborhood, property, and price point tells a different story. But that’s where possibility often lies.
A motivated seller, a well-priced home, and the right negotiating strategy can create exceptional value, even in a market without widespread price declines.
Why Consumer Confidence Could Be a Game Changer
Another factor I’m watching closely? Consumer confidence. The Conference Board reported an improvement back in October, even before the election. As households gain greater clarity about their employment prospects and financial futures, I believe more buyers will feel comfortable moving forward with life-changing decisions. Potential reductions in healthcare costs, should future policy changes deliver them, could also provide households with additional financial flexibility.
These developments aren’t guaranteed, and buyers shouldn’t build their budgets around anticipated savings. But taken together, they represent potential catalysts for stronger housing demand in the years ahead.
And when confidence returns, competition often follows.
The Mortgage Rate Dilemma: Is Waiting Actually Worth It?
The most common argument I’m hearing against buying these days comes down to one number: the mortgage rate. And to be clear, I understand why. Mortgage rates have a significant impact on affordability, and Freddie Mac’s October 29 national average stood at 7.24%. But here’s what I encourage buyers to consider: Waiting for a lower interest rate doesn’t necessarily mean waiting for a better financial opportunity. Sure, a lower rate may reduce borrowing costs, but what happens if home prices rise in the meantime?
Let’s look at two hypothetical scenarios.
Scenario 1: Buy Now and Refinance Later
Imagine purchasing a $1 million home today with a 20% down payment.
With a 30-year mortgage at an assumed 7% interest rate, your monthly principal and interest payment would be approximately $5,322. That’s the payment you need to be comfortable making today. But it doesn’t necessarily have to remain your payment forever.
Let’s say mortgage rates fall to 5% three years from now.
If you qualify to refinance while maintaining your original payoff schedule, your monthly principal and interest payment could drop to approximately $4,357. That’s nearly $1,000 in monthly savings, or more than $11,500 per year. Even factoring in an estimated $15,000 in refinancing costs, those savings could offset the added expense in approximately 16 months.
The advantage? You’ve already secured your purchase price and begun building equity while retaining the potential to benefit from lower rates in the future.
Scenario 2: Wait Three Years for Rates to Fall
Now let’s consider what happens if you decide to wait. Assume that same $1 million home appreciates at a modest 3% annually over the next three years. By the time you’re ready to purchase, its price would have climbed to approximately $1.09 million. With a 20% down payment, you’d need roughly $18,500 more in upfront cash than you would today. And even with a more favorable 5% mortgage rate, your monthly principal and interest payment would be approximately $4,693.
In other words? While you’ve secured a lower interest rate, you’re now financing a more expensive property.
The Takeaway: The Lowest Rate Isn’t Always the Best Deal
With these scenarios in mind, I always encourage buyers to look beyond mortgage rates when evaluating the right time to purchase. Buying today may allow you to lock in a favorable purchase price, begin accumulating equity, and potentially refinance if borrowing costs decline. Waiting could mean securing a lower rate, but it could also mean facing higher home prices, increased competition, and less negotiating leverage at the same time.
Of course, these storylines are illustrations, not predictions or guarantees. They exclude property taxes, insurance, maintenance, association fees, and purchase closing costs, and they aren’t intended as a complete comparison of buying versus renting. Refinancing also requires qualification, and there’s no guarantee rates will decline. Simply put? Any buyer entering today’s market should be fully comfortable carrying their existing mortgage if refinancing never becomes an option.
My Three-Year Outlook: A Market Poised for a Comeback
Looking ahead, I’m optimistic about what the next three years could bring. Imagine a market where returning jobs, revitalized nonprofit activity, and an influx of young professionals coincide with more favorable borrowing costs. That combination could unleash a substantial wave of housing demand across Washington, DC, Maryland, and Northern Virginia. I believe the potential exists for an exceptional bounceback, one that could reshape the competitive landscape for buyers.
But even with that optimism, I always come back to one essential principle: The right home purchase is one you can comfortably afford today, regardless of how quickly the market recovers.
A strong long-term investment should never depend entirely on a favorable short-term forecast.
The Bottom Line: Opportunity Favors the Prepared Buyer
My advice is simple: If you’re financially ready to buy, don’t let the pursuit of perfect market conditions prevent you from recognizing a promising opportunity. Find a home that meets your needs, negotiate strategically, and make sure the monthly payment fits comfortably within your budget.
If mortgage rates fall, refinancing may give you the chance to improve your financial position down the road. But there’s one thing you can never refinance: the price you paid for your home. And if confidence returns, demand accelerates, and competition intensifies, the opportunities available in today’s market may look very different a few years from now.
So at the end of the day, the best time to buy isn’t necessarily when everyone around you exudes market conviction. Sometimes, it’s simply when you know the moment is right for your distinct budget, timeline, and goals.
Ready to make moves sooner rather than later? Get in touch today by filling out the form on this page, calling 202.280.2060, or emailing our team at connect@jennsmira.com.

Put Us To Work For You
Book a consultation with our team today.