



How Much Does It Cost to Upsize Your Home?
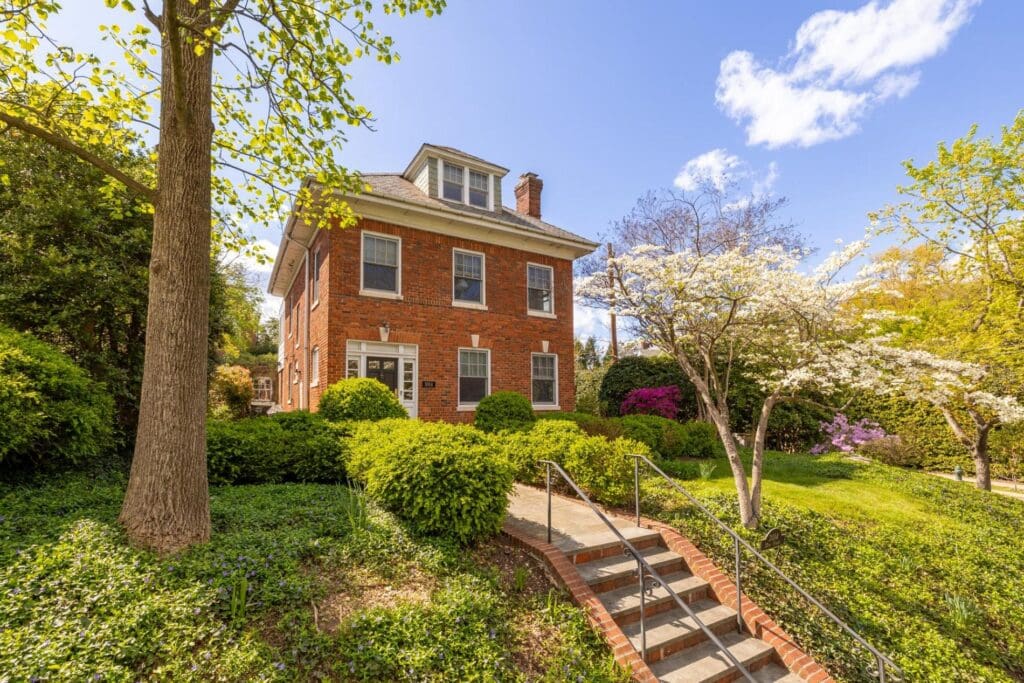
In search of more bedrooms, a bigger backyard, a dedicated home office, or simply some much-needed breathing room?
Whatever’s driving your decision to upsize, moving into a larger home is an exciting next chapter. But how much will that extra square footage actually cost you? Spoiler alert: There’s more to consider than just the difference between your current home’s price tag and your next one.
Before making your move, here’s what you need to know about the true cost of upsizing today.
The Price Difference
Let’s start with the obvious: A bigger home typically comes with a bigger price tag. Depending on your location, neighborhood, and must-have features, upgrading from a $700,000 home to a $1,050,000 property means accounting for a $350,000 difference. But that doesn’t necessarily mean you’ll need an additional $350,000 in cash. The equity you’ve built in your current home can help fund your next purchase, potentially covering a substantial portion of your down payment.
Our advice? Start by determining how much equity you have and what you can comfortably afford before falling in love with a new property.
Looking to buy a home in DC? Add these topics to your lineup!
Closing Costs (Twice!)
Here’s an expense that can catch homeowners off guard: When you’re selling one home and buying another, you’re dealing with two separate transactions. On the selling side, you’ll need to account for agent compensation, transfer taxes, and other closing expenses. On the buying side, expect lender fees, title charges, appraisal costs, and prepaid expenses. Depending on your location and financing, buyer closing costs can run approximately 2% to 5% of the purchase price, although the exact amount varies.
And don’t forget: Some costs, including real estate commissions and transfer taxes, may be negotiable.
A Bigger Mortgage Payment
Even if you’ve built substantial equity in your current home, upsizing could mean taking on a larger mortgage. Your monthly payment will depend on several factors, including your new loan amount, interest rate, down payment, and loan term. And there’s another important consideration: If you secured your current mortgage when rates were significantly lower, moving could mean trading that favorable rate for a higher one.
Before committing, compare your current monthly payment with your projected new payment, including principal, interest, taxes, and insurance.
Higher Property Taxes and Insurance
This just in: More house can also mean more revolving expenses. A higher property value may translate to a larger property tax bill, while additional square footage, upgraded finishes, and increased replacement costs could raise your homeowners insurance premiums. Keep in mind that property taxes vary considerably across DC, Maryland, and Virginia, so location matters just as much as purchase price.
And of course, a move across county or state lines could make a meaningful difference in your annual expenses, too.
Maintenance, Utilities, and Upkeep
More space means more room to spread out, but it also means more space to heat, cool, clean, and maintain.
Depending on the property, you could be looking at:
- Higher electricity, heating, and cooling bills
- Increased landscaping and lawn care expenses
- More costly roof, HVAC, and exterior repairs
- Additional cleaning and general maintenance
- Higher HOA or community fees
A good rule of thumb? Consider setting aside approximately 1% to 2% of your home’s value annually for maintenance and repairs, adjusting for the property’s age and condition.
Moving Expenses and New Furnishings
That extra guest bedroom isn’t going to furnish itself! Beyond hiring movers, purchasing packing supplies, and potentially paying for temporary storage, upsizing often comes with a few unexpected shopping trips. Think additional furniture, window treatments, rugs, lighting, and outdoor essentials.
You don’t have to furnish every room immediately, but it’s still smart to build these expenses into your budget from the beginning.
Thinking about selling your home soon? Explore these related resources for more advice!
- How To Sell Your Home In One Month Or Less
- 9 Small Details that Can Make or Break Your Home Sale
- Things to Know About Selling Your Home As-Is
The Cost of Buying Before Selling
Found your dream home before your current property has sold? You may need a strategy to bridge the financial gap. Depending on your circumstances, options could include a bridge loan, home equity line of credit (HELOC), or financing that allows you to purchase before selling. Each comes with its own costs, qualifications, and risks. You may also need to carry two mortgages temporarily, which can put additional pressure on your monthly budget.
Working with an experienced real estate agent and lender can help you determine which approach makes the most financial sense.
So, Is Upsizing Worth It?
Absolutely…that is, if the move aligns with your lifestyle, long-term goals, and financial comfort zone. The key is looking beyond the listing price and understanding the full picture, from upfront transaction costs to ongoing monthly expenses.
And remember: Upsizing doesn’t always mean spending dramatically more. A strategic move to a different neighborhood, a property with better value per square foot, or a home with room to grow could help you get more of what you want without stretching your budget too far.
Upsize With Jenn Smira
Thinking about making a move in the DC area? Whether you’re looking for an extra bedroom, more outdoor space, or an entirely new neighborhood, our team is here to help you evaluate your options and maximize your current home’s value so you can make your next move with confidence.
Get in touch with us by filling out the form on this page, calling us at 202.280.2060, or emailing connect@jennsmira.com.

Put Us To Work For You
Book a consultation with our team today.